A tax-deferred investment lets you postpone taxes on contributions, earnings, or both until you withdraw money. What is a tax-deferred investment? It’s usually an account or financial product designed to delay taxation while your savings remain invested.
You may owe ordinary income tax when taxable funds leave the account. Tax deferral can support long-term growth because annual interest, dividends, and capital gains aren’t reduced by yearly taxes inside the account. Still, deferred doesn’t mean tax-free. The bill normally arrives later, and withdrawal rules may limit access to your money.
| Key point | What it means |
| Main benefit | Taxes are postponed while eligible money remains invested |
| Common examples | Traditional 401(k)s, traditional IRAs and deferred annuities |
| Tax on withdrawals | Taxable distributions are generally treated as ordinary income |
| Early access | Income tax and an additional 10% federal tax may apply |
| Required withdrawals | Many account owners must begin RMDs at age 73 |
| Best use | Long-term goals, especially retirement |
| Main limitation | Future tax rates and withdrawal needs are uncertain |
Direct answer: A tax-deferred investment postpones federal income tax on eligible contributions, investment earnings, or both. Your untaxed balance can compound inside the account. You generally pay tax when you take a taxable distribution, often during retirement. Account rules, penalties, fees, and required withdrawals can affect the final benefit.
How Does Tax Deferral Work?
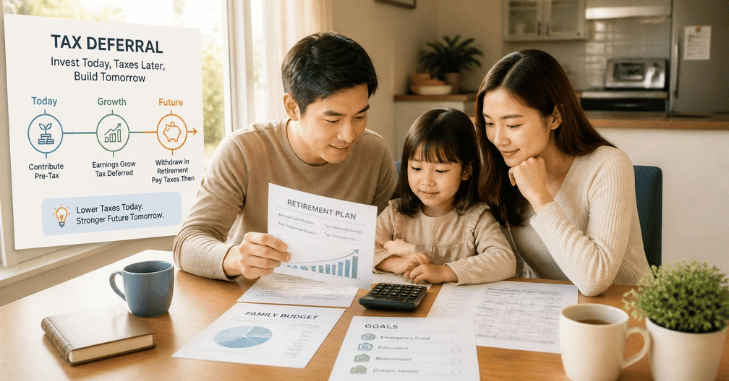
What Is a Tax-Deferred Investment? Tax deferral changes when you pay tax, not necessarily how much you’ll eventually owe. In a regular taxable brokerage account, interest and dividends may create annual tax bills. Selling an investment at a profit may also trigger capital gains tax.
A qualified deferred account generally shields those earnings from current federal income tax while the money remains in it. Traditional retirement accounts may offer another benefit. Contributions can be made with pretax money or may qualify for a deduction.
That can reduce current taxable income, depending on the account and your eligibility. Traditional IRA contributions, for example, may be deductible under IRS rules. When you withdraw taxable money, the distribution is generally included in your income. Your actual cost depends on the tax rules and your tax bracket at that time.
A Simple Growth Example
Suppose you invest $10,000 and earn 6% per year for 20 years. This example assumes no further deposits, withdrawals, or fees.
| Account treatment | Simplified result |
| No annual tax drag | About $32,071 |
| Earnings reduced to 4.8% after yearly tax | About $25,529 |
| Difference before withdrawal tax | About $6,542 |
This example doesn’t prove that a deferred account always produces a better after-tax result. It shows why postponing annual taxes can increase the amount available for compounding. Your outcome depends on returns, fees, contribution deductions, withdrawal taxes, and your investment period.
What Is a Tax-Deferred Investment Account?
The term can describe several account types and financial products. Their investments, fees, contribution rules, and withdrawal terms aren’t identical.
Traditional 401(k)
A traditional 401(k) is an employer-sponsored retirement plan. Eligible salary contributions are generally made before federal income tax, although Social Security and Medicare taxes may still apply. Investments grow without annual federal income tax inside the plan.
Taxable distributions are usually included in income when withdrawn. A workplace plan may also offer an employer match, which can make it a valuable first place to save.
Traditional IRA
A traditional individual retirement arrangement provides tax-deferred growth. Contributions may be deductible, but the deduction may depend on income, filing status, and workplace retirement plan coverage.
You can hold different investments inside an IRA. Depending on the provider, choices may include mutual funds, exchange-traded funds, stocks, bonds, or deposit products.
For a lower-volatility option, Writingley’s IRA CD guide explains how a certificate of deposit can be held within a traditional or Roth retirement account.
Tax-Deferred Annuity

A deferred annuity is an insurance contract designed to accumulate value before income payments or withdrawals begin. Earnings generally aren’t taxed until they’re withdrawn.
Annuities can have surrender charges, administrative expenses, investment fees, and complex contract terms. Withdrawals may also be treated as earnings first, depending on the contract and whether it is qualified or nonqualified.
Review costs, guarantees, liquidity, and the insurer’s financial strength before purchasing one. Writingley’s private annuity overview covers another annuity arrangement used in some estate-planning situations.
Other deferred arrangements
Some employer retirement plans, such as 403(b) plans, also allow eligible pretax savings. Certain government and nonprofit employees may have access to 457 plans.
Tax treatment differs by account. Don’t assume that every retirement product has the same contribution limits, distribution rules, creditor protections, or investment choices.
Tax-Deferred vs. Tax-Free vs. Taxable
These terms describe three distinct tax treatments.
| Account type | Contribution treatment | Growth treatment | Withdrawal treatment |
| Tax-deferred | May be pretax or deductible | No current tax on eligible earnings | Taxable distributions generally create income |
| Tax-free Roth | Made with after-tax money | No annual tax inside the account | Qualified withdrawals are generally tax-free |
| Taxable account | Made with after-tax money | Dividends, interest and realized gains may be taxed | The principal isn’t taxed again; gains may be taxable |
A Roth IRA isn’t usually described as tax-deferred in the same sense as a traditional IRA. Roth contributions don’t provide an upfront deduction, but qualified withdrawals may be tax-free. The IRS distinguishes traditional and Roth arrangements based on these contribution and distribution rules.
Some retirement savers use both account types. Holding pretax and Roth savings may provide more control over taxable income during retirement. People with eligible workplace plans may also consider advanced Roth funding methods.
Writingley’s mega backdoor Roth IRA guide explains how certain employees can convert voluntary after-tax plan contributions to Roth savings.
Benefits of Delaying Taxes

Tax deferral may provide several advantages.
- More money stays invested. Annual taxes don’t reduce eligible earnings inside the account.
- Current taxable income may fall. Pretax contributions or deductible IRA deposits can reduce taxable income when requirements are met.
- Compounding can occur on a larger balance. Money that might have gone toward current tax remains invested.
- Retirement income can be planned. You may have some control over when voluntary withdrawals occur.
- Saving becomes automatic. Workplace payroll contributions can make regular investing easier.
These benefits are strongest when the account has reasonable costs, suitable investments, and enough time to grow.
Risks and Withdrawal Rules
The tax benefit shouldn’t be considered in isolation. Access restrictions and future taxes matter.
Early Distributions May Cost More
Most taxable retirement-plan distributions are subject to income tax. A withdrawal before age 59½ may also face an additional 10% federal tax unless an exception applies. Specific exceptions vary by account and circumstance.
An annuity may impose a separate surrender charge. That means one withdrawal could create both a contract fee and a federal tax consequence.
Future Tax Rates Are Unknown
You may pay less tax during retirement if your taxable income falls. You could also face the same or a higher marginal rate.
Future tax law, other retirement income, Social Security benefits, pension payments, and required withdrawals can all affect your bracket. Tax deferral works best when evaluated as part of a broader income plan.
Required Minimum Distributions Can Reduce Control
Traditional IRA owners generally must begin required minimum distributions at age 73 under current rules. Many workplace-plan participants can delay RMDs until retirement if their plan permits it and they aren’t 5% owners.
An RMD creates taxable income even when you don’t need the money for spending. Large pretax balances can lead to larger mandatory distributions later.
Fees Still Reduce Returns
Tax treatment can’t rescue an expensive or unsuitable product. Check:
- Account administration fees
- Fund expense ratios
- Advisory charges
- Trading costs
- Annuity mortality and expense charges
- Rider fees
- Surrender periods
Compare the after-fee value with simpler alternatives before committing money.
When Does Tax-Deferred Investing Make Sense?

This approach may be a good fit when you’re saving for retirement, have a long investment horizon, and can leave the money untouched.
It may be especially useful when:
- Your employer offers matching contributions.
- You expect your taxable income to be lower after retiring.
- You’ve built an emergency fund.
- You don’t need the invested money for near-term expenses.
- Account fees and investment options are competitive.
- You want to diversify savings across different tax treatments.
Tax deferral may be less attractive when you need flexible access, expect a much higher future tax rate, or face high product fees. A taxable brokerage account may offer fewer tax breaks, but it generally provides easier access and no RMDs from retirement accounts.
The right choice may involve several account types rather than one. You can review Writingley’s broader ta x planning resources when comparing current deductions, deferred accounts, and tax-free options.
How to Evaluate an Account Before Investing?

- Confirm the tax treatment. Determine whether contributions are pretax, deductible, after-tax, or nondeductible.
- Review access rules. Check withdrawal restrictions, penalties, surrender periods, and permitted loans.
- Compare all fees. Include account, fund, advisory, insurance, and transaction costs.
- Study the investments. Make sure the risk level and time horizon match your goal.
- Plan for distributions. Estimate how withdrawals and RMDs could affect future taxable income.
A financial adviser or tax professional can help when your decision involves rollovers, annuities, large conversions, inherited accounts, or several retirement income sources.
Apart from that, if you want to know about the article, Augusta Rule then visit our Tax category.
Frequently Asked Questions
What is a tax-deferred investment?
Is tax-deferred the same as tax-free?
Do you pay capital gains tax on a traditional IRA withdrawal?
Can you withdraw deferred money at any time?
Are tax-deferred accounts always better?