The stock market. An IRA CD combines a tax-advantaged individual retirement arrangement with a certificate of deposit. It can provide a fixed interest rate, predictable earnings, and protection from stock-market losses. The trade-off is limited access to your money and less long-term growth potential than many market-based investments.
An account like this may suit someone nearing retirement or anyone who values stability. It’s less likely to meet the needs of a younger investor seeking decades of growth.
| Key point | What it means |
| Account structure | A certificate of deposit held inside a traditional or Roth individual retirement arrangement |
| Return | Usually a fixed annual percentage yield for a set term |
| Risk level | Low when held at a federally insured institution and kept within coverage limits |
| Access | Withdrawals may trigger bank penalties, tax consequences, or both |
| Best suited to | Conservative savers and people approaching retirement |
| Main limitation | Lower growth potential and reduced liquidity |
Direct answer: An IRA CD is a bank deposit held within a retirement account. Your deposit earns a stated rate for a fixed period while receiving the tax treatment of the retirement account. It offers stability, but early access can cause multiple penalties, and inflation may reduce the value of its returns.
What Is An IRA CD?

This product has two distinct parts. The retirement account provides the tax structure. The certificate provides the interest rate, term, and maturity date. You generally choose a term ranging from several months to several years. The bank pays interest according to the account’s annual percentage yield.
When the term ends, you can renew it, move the balance to another eligible investment, or arrange a qualified withdrawal. A traditional account usually allows tax-deferred growth. Taxes are generally due when you take taxable distributions.
A Roth version uses after-tax contributions and can provide tax-free qualified withdrawals when its requirements are met. The IRS defines individual retirement arrangements as accounts that provide tax-advantaged retirement investing.
The product should not be confused with a standard bank certificate. A standard certificate has no retirement-account tax treatment. It also isn’t governed by annual retirement contribution limits or retirement distribution rules.
How Does It Work?
You open the account through a bank, credit union, or another institution that offers retirement certificates. You then fund it through a contribution, transfer, or rollover that meets the applicable rules. The institution offers a stated rate for a specific term. Your rate normally remains unchanged until maturity.
That makes the future account value easier to estimate than the value of a stock or mutual fund. Consider a simplified example. You place $10,000 into a two-year certificate paying a fixed 4% annual yield. If interest compounds annually and you make no withdrawals, the balance would be about $10,816 after two years.
The precise result depends on the institution’s compounding method and account terms. At maturity, many institutions provide a short grace period. During that period, you may be able to withdraw, transfer, or reinvest the balance without a bank-imposed early-termination charge.
7 Things to Check Before Opening an IRA CD

1. The Annual Percentage Yield
Compare annual percentage yields rather than advertised interest rates alone. APY accounts for compounding and gives you a clearer way to compare products.
A higher yield isn’t automatically the right choice. Check the term, minimum deposit, renewal conditions, and early-withdrawal charge as well.
2. The Length Of The Term
A longer term may pay more, but it also limits your access for longer. Think about when you may need the money.
Short terms provide more flexibility. Long-term can make sense when the rate is attractive, and the funds won’t be needed soon.
3. Both Layers of Withdrawal Rules
Taking money out before maturity may cause a bank penalty. Taking a nonqualified retirement distributioattractive andte income taxes and an additional federal tax. These are separate issues. A withdrawal can satisfy the bank’s rules yet still have tax consequences.
It can also satisfy federal retirement rules while triggering the institution’s early-termination charge. Read the deposit agreement and consult a qualified tax professional before taking an early distribution.
4. Federal Insurance Coverage

Deposit products at an FDIC-insured bank may be protected by federal deposit insurance. All qualifying retirement deposits owned by the same person at the same insured bank are generally combined and insured up to $250,000.
For example, two retirement certificates with balances of $150,000 each at one bank would total $300,000 in the same ownership category. Under the standard limit, $50,000 could be uninsured. Accounts held at separate insured banks may receive separate coverage.
Credit union accounts may receive comparable protection through the National Credit Union Share Insurance Fund. Confirm an institution’s insured status before depositing money.
5. The Current Contribution Limit
For 2026, total contributions across a person’s traditional and Roth arrangements are generally limited to $7,500. The limit rises to $8,600 for eligible people aged 50 or older. Contributions also cannot exceed taxable compensation when compensation is lower than the annual limit.
Rollovers generally don’t count against that annual contribution limit. The rules for eligibility, deductions, and Roth contributions can depend on income and workplace-plan coverage.
6. Inflation Risk
The principal may remain stable, but its purchasing power can fall. A fixed 3% return loses ground when prices rise faster than 3%.
This matters most over long periods. Stocks and other growth assets can fluctuate sharply, but they have more potential to outpace inflation. Holding every retirement dollar in fixed deposits could make it harder to fund a long retirement.
7. Your Place In The Retirement Timeline
Someone retiring soon may value stable funds for near-term expenses. Someone with 30 years before retirement may need greater growth.
One practical framework is to match the term to a future spending need. Money intended for expenses in two years could be placed in a two-year product. Funds intended for use decades later may be better suited to investments with higher expected growth, depending on risk tolerance.
Traditional vs. Roth Retirement Certificates
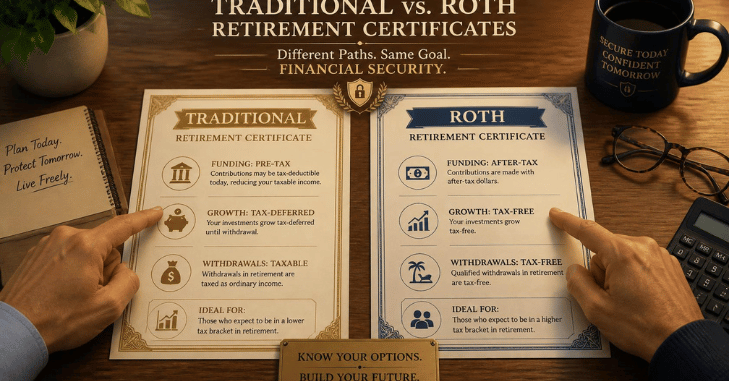
| Feature | Traditional account | Roth account |
| Contributions | May be deductible when requirements are met | Made with after-tax money |
| Growth | Tax-deferred | Potentially tax-free |
| Qualified withdrawals | Usually taxed as ordinary income | Generally tax-free when requirements are met |
| Required distributions | May apply to the original owner | Generally don’t apply to the original owner |
| Income restrictions | Deduction eligibility may be limited | Direct contributions may be limited |
The IRS states that required minimum distributions may begin after age 73 for people subject to the current rules. Roth accounts generally receive different treatment for the original owner.
Tax rules depend on your circumstances and can change. Verify the current requirements before contributing or withdrawing.
Benefits and Drawbacks
Pros
- The return is predictable during the term.
- The account avoids direct stock-market volatility.
- Qualifying deposits may receive federal insurance.
- It can support short-term retirement spending plans.
- A ladder can create recurring maturity dates.
Cons
- Returns may trail inflation.
- Growth potential is usually lower than with stocks.
- Early access may cause two separate penalties.
- Funds remain locked until maturity.
- Renewal rates may be lower than the original rate.
- Contribution and distribution rules add complexity.
Could a Ladder Improve Flexibility?
A ladder divides your money across several maturity dates. Instead of putting $30,000 into one three-year product, you might divide it among one-, two-, and three-year terms.
The first portion matures after one year. You can use the money or reinvest it into a new longer-term certificate. Another portion becomes available the following year.
This structure creates regular access points. It also reduces the risk of committing the entire balance to a single rate. It doesn’t eliminate early-withdrawal rules or inflation risk.
Who Should Consider One?

This option may fit you when:
- Preserving principal matters more than maximizing growth.
- Retirement is close.
- You need a predictable return for a known future expense.
- Stock market losses would cause you to abandon your plan.
- The deposit represents one conservative part of a diversified portfolio.
It may be a poor fit when you have a long investment horizon, need flexible access, or want stronger long-term growth. It’s also less attractive when its yield falls well below inflation or competitive low-risk alternatives.
Conclusion
An IRA CD can be a smart choice for retirement savers who value stability, predictable returns, and protection from market volatility. While it offers the tax advantages of an IRA combined with the guaranteed interest of a certificate of deposit, it also comes with important trade-offs, including limited liquidity, lower long-term growth potential, and possible penalties for early withdrawals.
Before opening an IRA CD, compare interest rates (APYs), term lengths, federal insurance coverage, renewal policies, and withdrawal rules to ensure the account aligns with your retirement goals. Consider how inflation may affect your purchasing power over time and whether an IRA CD should be only one part of a diversified retirement portfolio.
Apart from that, if you want to know about the article IRA Interest Rates, then visit our Retirement category: